If you paid a non-employee $2,000 or more during tax year 2026, you must file Form 1099-NEC for that payee. Start here: split what you paid into nonemployee compensation, cash tips and qualified overtime, look up the Treasury Tipped Occupation Code if any of it was tips, and get both copies out by 1 February 2027.
TL;DR:
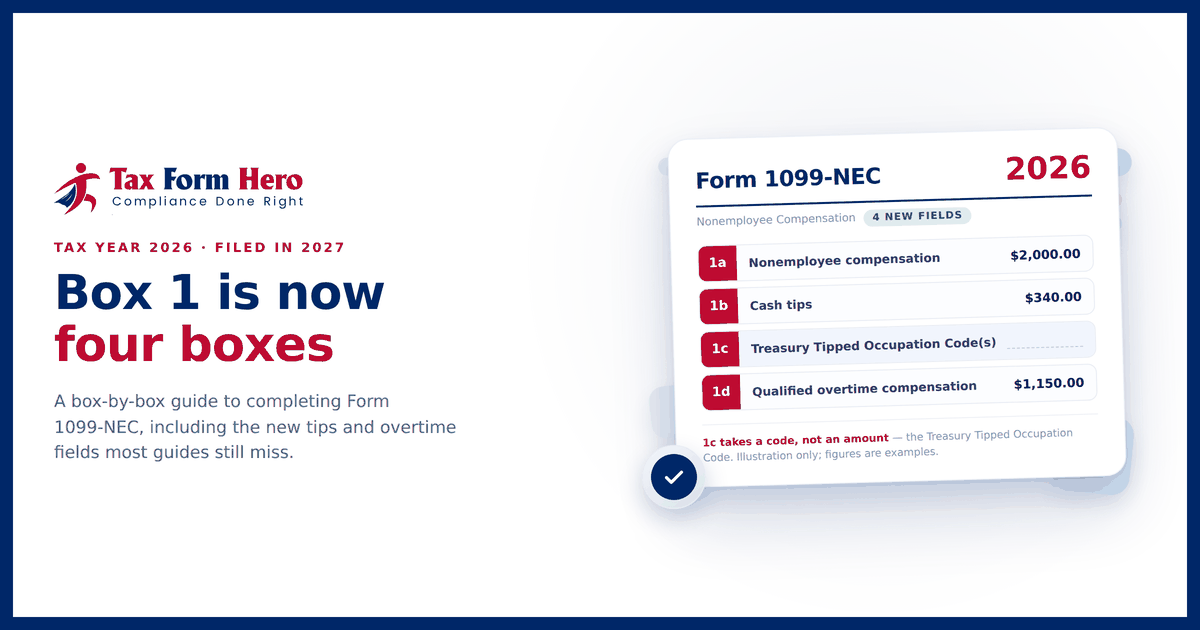
- Box 1 is now four fields: 1a nonemployee compensation, 1b cash tips, 1c the Treasury Tipped Occupation Code and 1d qualified overtime compensation.
- Box 1c takes a code, not a dollar amount — the single most common error on the 2026 form.
- The filing threshold rose from $600 to $2,000, so this year’s contractor list is shorter than last year’s.
- Box 2 is a checkbox for direct sales of $5,000 or more, and box 3 now carries excess golden parachute payments.
- Any backup withholding in box 4 makes the form required, however small the payment was.
- Both the IRS copy and the recipient copy are due 1 February 2027, with no separate paper-filing extension.
If you are still gathering names, addresses and taxpayer IDs, start with preparing your 1099-NEC data instead. This guide assumes the data is in front of you and the question is where to put it.
What changed on Form 1099-NEC for tax year 2026
Four changes, all of which affect how you complete the form rather than merely when you file it.
| Change | What it means when you fill the form in |
|---|---|
| Box 1 split into 1a–1d | Nonemployee compensation, cash tips, Treasury Tipped Occupation Code(s) and qualified overtime compensation are now reported in separate fields. Boxes 1a, 1b and 1d are dollar-amount fields; box 1c takes up to two occupation codes, not an amount. A single lump sum in 1a is no longer a complete return for a payee who received any of the others. |
| Threshold raised to $2,000 | Up from $600, for payments made after 31 December 2025, indexed for inflation after 2026. Your contractor list will be shorter than last year's. |
| Box 3 in use | Excess golden parachute payments now sit on the 1099-NEC rather than the 1099-MISC. Most filers will never touch it; the ones who do would otherwise put it on the wrong form. |
| Deadline moves to 1 February 2027 | The usual 31 January falls on a Sunday, so both the IRS copy and the recipient copy are due the next business day. |
The wider set of tax year 2026 changes — including the 1099-K threshold and the retirement of the IRS FIRE system — is covered on our tax year 2026 changes page.
If you would rather not do this on paper, e-file Form 1099-NEC online with TaxFormHero instead.
The payer and recipient blocks
These sit above the numbered boxes and cause more rejected returns than the amounts do.
Payer information
Your business's legal name exactly as the IRS holds it, the full address, a telephone number, and your Employer Identification Number. Use the name on your IRS notices rather than your trading name. If the two differ, the notice wins.
Recipient information
The payee's legal name and taxpayer identification number, taken from a signed Form W-9 rather than from an invoice. An invoice gives you the name a business trades under; the W-9 gives you the name the IRS has on file, and those are frequently different.
For an individual the surname and given name go in their own fields. For a business the full legal entity name goes in the company name field and is not split. A single-member LLC is usually matched against its owner's name unless it has elected corporate treatment — the first line of the W-9 is the one that matters.
The taxpayer ID is nine digits. Punctuation is cosmetic; leading zeros are not, and a spreadsheet formatted as a number will silently eat them. If you are filing more than a handful of forms, run the pairs through IRS TIN matching before you file rather than after.
Account number and the second TIN notice
The account number is required when you file more than one 1099-NEC for the same recipient, and it is useful even when you do not — it is what identifies which return a later correction replaces. The second TIN notice box is ticked only if the IRS has notified you twice within three calendar years that this payee's name and TIN do not match.
Box by box
Box 1a — Nonemployee compensation
The ordinary case: fees, commissions, prizes and awards for services, and other compensation paid to someone who is not your employee, in the course of your trade or business. Parts and materials you paid for as part of the service belong here too.
Enter the total actually paid during the calendar year, not the amount invoiced. A December invoice settled in January belongs on next year's form.
Boxes 1b, 1c and 1d — tips and overtime
These are the boxes most guides have not caught up with, and the ones your accounting export probably does not produce yet.
| Box | What goes in it |
|---|---|
| 1b | Cash tips paid to the payee — a dollar amount |
| 1c | The Treasury Tipped Occupation Code (TTOC) for the occupation those tips were earned in. A code, not a dollar amount. Where tips came from more than two occupations, give the code for any two of them. |
| 1d | Qualified overtime compensation — a dollar amount |
If your books have been recording one combined figure, splitting it retrospectively in January is painful and error-prone. Work out where tips and overtime live in your accounting system now, while the year is still open.
Box 2 — Direct sales checkbox
A checkbox, not an amount. Tick it if you sold $5,000 or more of consumer products to this person on a buy-sell, deposit-commission or similar basis for resale anywhere other than a permanent retail establishment. The dollar figure itself is never entered. The same election can be reported in box 7 of Form 1099-MISC instead — pick one, not both.
Box 3 — Excess golden parachute payments
New to this form. Excess parachute payments under section 280G, previously reported on Form 1099-MISC. If you do not know whether you have made one, you almost certainly have not.
Box 4 — Federal income tax withheld
Almost always backup withholding at 24%, which applies when a payee has not given you a TIN, has given you an obviously incorrect one, or the IRS has told you to start withholding.
The rule people miss: if you withheld any federal income tax, you must file a 1099-NEC for that payee regardless of the amount paid. The $2,000 threshold does not apply. A $400 payment with backup withholding still gets a form.
Boxes 5, 6 and 7 — State information
State tax withheld, the state abbreviation with your state payer number, and the state income. The form carries two rows so a single payee can be reported to two states.
These boxes are for the state's benefit, not the IRS's. Whether you need to file with the state at all depends on the state and on whether it participates in the Combined Federal/State Filing Program — in a participating state the federal filing is forwarded for you.
The whole form at a glance
| Field | Contents | Common error |
|---|---|---|
| Payer block | Legal name, address, phone, EIN | Trading name instead of legal name |
| Recipient block | Legal name, address, TIN | Name and TIN belong to different entities |
| Account number | Your reference for this payee | Left blank on a second form for the same payee |
| Box 1a | Nonemployee compensation | Tips and overtime lumped in |
| Box 1b | Cash tips | Omitted entirely |
| Box 1c | Treasury Tipped Occupation Code(s) — up to two, not an amount | A dollar figure entered where a code belongs |
| Box 1d | Qualified overtime compensation | Omitted entirely |
| Box 2 | Direct sales checkbox | A dollar amount entered instead of a tick |
| Box 3 | Excess golden parachute payments | Still reported on the 1099-MISC |
| Box 4 | Federal income tax withheld | Form not filed because the payment was under the threshold |
| Boxes 5–7 | State tax, state number, state income | State income left blank when state tax is withheld |
Payments that belong on a different form
Reporting a payment twice is worse than not reporting it, because the payee receives two forms for one payment and has to explain the gap.
| Payment | Correct form | Why |
|---|---|---|
| Fees for legal services to an attorney | 1099-NEC box 1a | Reportable even if the attorney is a corporation |
| Gross proceeds to an attorney, e.g. a settlement | 1099-MISC box 10 | Not a fee for services rendered to you |
| Rent, royalties, prizes not for services | 1099-MISC | Not compensation for work |
| Medical and health care payments | 1099-MISC box 6 | Reportable to corporations as well |
| Anything paid by card or payment network | 1099-K, filed by the processor | You do not report it at all |
| Employee wages | W-2 | Paying from a different account does not change the classification |
| Payments to a corporation for services | Usually none | Attorneys are the notable exception |
If you are unsure whether someone is a contractor at all, the IRS guidance on worker classification is the place to settle it. Getting this wrong is more expensive than any box on the form.
Which copy goes where
| Copy | Goes to | Note |
|---|---|---|
| Copy A | The IRS | The red scannable copy. Do not print it from the IRS website and post it — an unscannable Copy A can draw a penalty. E-filing removes the problem entirely. |
| Copy 1 | State tax department | Only where the state requires it |
| Copy B | The recipient | Due the same day as the IRS copy |
| Copy 2 | The recipient | For filing with their state return |
| Copy C | You | Your records |
Recipient copies can be delivered electronically, but only with the recipient's prior consent, given in a way that shows they can open the format it will arrive in. Electronic delivery collects and records that consent; without it, paper is the default.
Deadlines and how to file
- 1 February 2027 — Copy A to the IRS and Copy B to the recipient, for tax year 2026. There is no later deadline for electronic filing of the 1099-NEC, unlike some other forms in the series.
- Ten or more information returns of all types combined means you must file electronically. It is an aggregate: nine 1099-NECs and two W-2s puts you over.
- Paper filing needs a Form 1096 transmittal. Electronic filing does not.
One change worth knowing if you have filed electronically before: the IRS FIRE system retires on 19 November 2026, and IRIS becomes the intake system for the 2027 filing season. If your process depended on FIRE, it needs revisiting before January.
Penalties, and why this page does not print the amounts
The penalty for a late or incorrect information return is tiered by how late it is:
- Corrected within 30 days of the due date
- Corrected after 30 days but by 1 August
- Filed after 1 August, or not filed at all
- Intentional disregard, which carries a substantially higher penalty and no maximum
A separate penalty applies to failing to furnish the recipient copy, so a late filing can be penalised twice for the same form.
The dollar figures attached to each tier are adjusted for inflation every year, and small businesses have lower annual caps than large ones. Rather than print numbers that will be wrong by next season, the current amounts are in the IRS instructions for Forms 1099-MISC and 1099-NEC. If a guide quotes penalty amounts without a year attached, check them before relying on them.
Errors that get a return rejected or corrected
| Error | What happens | Fix |
|---|---|---|
| Name and TIN do not match IRS records | A CP2100 notice, and backup withholding obligations | Verify before filing; request a fresh W-9 if the pair disagrees |
| Leading zeros stripped from a TIN | Eight-digit number, rejected | Format the column as text before the export |
| Card payments included | Payee gets two forms for one payment | Exclude anything the processor reports on a 1099-K |
| Everything in box 1a | Understated tips and overtime reporting | Split 1b, 1c and 1d at source |
| Amount invoiced rather than paid | Figure disagrees with the payee's records | Report cash actually paid in the calendar year |
| Form omitted because the payment was small | Missing return where tax was withheld | File regardless of amount when box 4 is not zero |
Correcting a 1099-NEC you have already filed
The IRS treats corrections as two categories, and the difference decides how much work you have.
One-step corrections cover a wrong money amount, a wrong checkbox, or a return that should not have been filed at all. File a new return marked as corrected, with the right figures.
Two-step corrections cover a missing or incorrect payee TIN, an incorrect payee name, or the wrong type of return. These need one filing that voids the original with zero amounts, and a second that reports it correctly. Getting the name and TIN right the first time is the cheapest thing on this page.
Either way the recipient needs a corrected copy too, and the correction is transmitted as a new return.
Filling it in without the paperwork
Everything above is what the form asks for. E-filing Form 1099-NEC with TaxFormHero handles the mechanics around it: the boxes are laid out as described here including 1a to 1d, the transmittal is handled, recipient copies go out by download, secure link or post, and the filing stays retrievable for four years. You can build the whole filing and pay only when you submit it.
If the payee data is not clean yet, collecting a signed W-9 and verifying the name and TIN first will save you the correction described above.
Frequently asked questions
Do I need to file a 1099-NEC for payments under $2,000?
No, not on the threshold alone — for tax year 2026 the reporting threshold is $2,000, up from $600. But there is an exception that catches people out: if you withheld any federal income tax from the payee, you must file regardless of the amount. A $400 payment with backup withholding still needs a form.
What is the difference between boxes 1a, 1b, 1c and 1d?
They split what used to be a single figure, and one of them is not a figure. Box 1a is ordinary nonemployee compensation, 1b is cash tips and 1d is qualified overtime compensation — all dollar amounts. Box 1c is the Treasury Tipped Occupation Code, which identifies the occupation the tips were earned in. Putting a dollar amount in 1c, or putting everything in 1a, are the two most common errors on the 2026 form.
Do I send a 1099-NEC to an LLC?
It depends on how the LLC is taxed, not on the letters after its name. A single-member LLC or one taxed as a partnership generally gets a form; one that has elected corporate treatment generally does not. The payee tells you which on their Form W-9, which is the reason to collect one before you pay rather than in January.
What if I do not have the contractor's TIN by the deadline?
File on time anyway, and start backup withholding at 24% on payments going forward. A missing TIN is a correctable error; a missing return is not. Request the W-9 again in writing so you can show you asked.
Do I file a 1099-NEC if I paid by credit card or PayPal?
No. Payments made by card or through a third-party payment network are reported by the processor on Form 1099-K, and reporting them again on a 1099-NEC gives the contractor two forms for one payment.
Can I handwrite a 1099-NEC or print Copy A from the IRS website?
You can handwrite a paper form, but you cannot print Copy A from the IRS website and post it — the downloadable version is not the scannable red-ink copy and filing it can draw a penalty. Filing electronically removes the question entirely, and is mandatory once you have ten or more information returns of all types.
What is the 1099-NEC deadline for tax year 2026?
1 February 2027, for both the IRS copy and the recipient copy. The usual 31 January date falls on a Sunday that year, so it moves to the next business day. Unlike some other forms in the 1099 series, the 1099-NEC has no later deadline for electronic filing.
Do I have to file with my state as well?
Sometimes, and it depends on the state. Many states receive the federal filing automatically through the Combined Federal/State Filing Program; others want a direct filing, and a few want nothing. Boxes 5 to 7 exist for those that do.
IRS sources
- About Form 1099-NEC, Nonemployee Compensation
- Instructions for Forms 1099-MISC and 1099-NEC
- Form 1099-NEC (PDF)
- About Form 1099-MISC
- About Form W-9
- TIN Matching
- Backup Withholding
- Independent contractor or employee
- E-file information returns with IRIS
- About Form 1099-K

File Information Returns With Confidence
TaxFormHero supports 20+ IRS information returns, including 1099 and W-2 forms, with bulk Excel import, name/TIN matching and encrypted recipient delivery.
Explore TaxFormHero