Form 1099-MISC is the form people reach for when a payment does not fit anywhere else, and that is exactly what makes it awkward to complete. Form 1099-NEC is comparatively straightforward; Form 1099-MISC has several different payment categories, thresholds, and deadlines. There are three new boxes for tax year 2026, and a recipient deadline that two of its boxes quietly move by two weeks.
This guide walks the form from the payer block to Box 18, says what each box holds and the figure at which it becomes reportable, and flags the mistake most often made in it. Everything here is for tax year 2026 — the forms you file in 2027.
The short version
- The reporting threshold for rents, other income, medical payments and crop insurance rose from $600 to $2,000. Four other boxes did not move at all.
- Boxes 13a, 13b and 14 are new: cash tips, the Treasury Tipped Occupation Code, and qualified overtime. The two dollar boxes are already inside Box 3 — they are broken out of it, not added to it.
- Recipient copies are due February 1, 2027, or February 16, 2027 if the only boxes used are Box 8 or Box 10.
- Golden parachute payments left this form. For 2026 they go in Box 3 of the 1099-NEC.
- The FATCA filing requirement is now a checkbox with no box number. It used to be Box 13.
What changed on Form 1099-MISC for tax year 2026
Four things, and the first is the one that catches people out.
| Change | What it means when you fill the form in |
|---|---|
| The $600 threshold became $2,000 | It applies to the section 6041 categories only — Boxes 1, 3, 6 and 9. It is indexed for inflation after 2026. |
| Three new boxes | Box 13a (cash tips), Box 13b (Treasury Tipped Occupation Code) and Box 14 (qualified overtime compensation). |
| Golden parachute payments moved | They are reported in Box 3 of the 1099-NEC for 2026, not on this form. |
| FATCA is no longer Box 13 | It is a checkbox without a number, which is why the tips boxes could take 13a and 13b. |
Filing one yourself? You can e-file Form 1099-MISC online with TaxFormHero, an IRS-authorized e-filing platform.
There is no single 1099-MISC threshold
This is the single most useful thing to know about the form. The One Big Beautiful Bill Act raised the general information-return threshold to $2,000 for payments made after 31 December 2025, but it only reached the boxes that sit under section 6041. The rest were left exactly where they were.
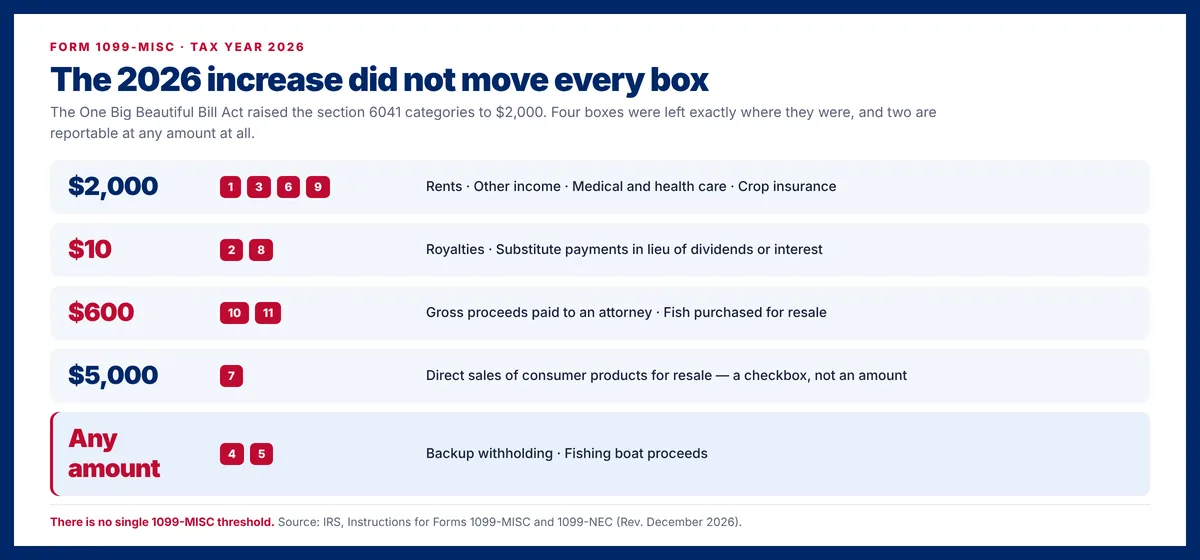
Two consequences worth holding on to. A $900 royalty is reportable even though it is nowhere near $2,000, because Box 2 is still a $10 box. And if you withheld backup withholding, the form is reportable no matter how small the payment was — Box 4 overrides every threshold on the form.
What you need before you start
- The recipient's legal name and TIN exactly as the IRS holds them, which means a signed Form W-9. A name and TIN that do not match is the most common cause of a notice.
- Your own business name, address, telephone number and TIN.
- The payment total for each box, for the calendar year, on a cash basis — what you actually paid in 2026, not what you accrued.
- Any federal income tax withheld, and any state withholding with the state identification number that goes with it.
If a contractor will not give you a TIN, you are expected to begin backup withholding rather than skip the form. That case is covered in what to do when a contractor refuses to provide a W-9.
The payer and recipient blocks
The left-hand column of the form is identification, and it is where rejections come from rather than penalties.
Payer information
Your legal business name, street address, city, state, ZIP and telephone number, then your TIN. Use the name the IRS has on file for your EIN. A trading name that differs from the registered name belongs on the second name line, not in place of the first.
Recipient information
The recipient's TIN, their name, and their address. For an individual, use the name on their Social Security card, not the name they invoice under. For a single-member LLC that has not elected corporate treatment, the IRS wants the owner's name and TIN, with the LLC name on the second line — a mismatch here is the classic reason a 1099 is rejected for an LLC.
Account number and the 2nd TIN notice
The account number is yours to define, and it is required when you file more than one 1099-MISC for the same recipient. Use something stable; it is what identifies the right form when you have to correct one. Tick the 2nd TIN notice box only if the IRS has told you twice in three calendar years that this recipient's TIN is wrong.
Form 1099-MISC, box by box
Every figure below is from the IRS Instructions for Forms 1099-MISC and 1099-NEC (Rev. December 2026). The third column is the one to read twice.
| Box | What goes in it | Reportable at | Most common error |
|---|---|---|---|
| 1 | Rents — office space, machinery, land, surface royalties | $2,000 | Rent paid to a real estate agent or property manager reported by the tenant; the agent reports it onward, not you |
| 2 | Royalties from oil, gas, other mineral properties, copyrights and patents | $10 | Skipped because the payment was under $2,000 — this box never moved |
| 3 | Other income, including prizes and awards not for services | $2,000 | Tips and overtime added on top instead of being broken out of this figure |
| 4 | Federal income tax withheld (backup withholding) | Any amount | Form not filed because the payment was under the threshold — if box 4 is not zero, file regardless |
| 5 | Fishing boat proceeds — a crew member’s share of the catch | Any amount | Reported as nonemployee compensation on the 1099-NEC |
| 6 | Medical and health care payments to a provider or supplier | $2,000 | Omitted for a corporation — this box is reportable to corporations too |
| 7 | Direct sales of consumer products for resale — a checkbox | $5,000 | An amount entered where an “X” belongs |
| 8 | Substitute payments in lieu of dividends or interest | $10 | Overlooked when calculating the recipient deadline — this box pushes it to February 16, 2027 |
| 9 | Crop insurance proceeds paid to farmers | $2,000 | Reported even though the farmer told the insurer the expenses were capitalized under section 278, 263A or 447 |
| 10 | Gross proceeds paid to an attorney — settlement money passing through, not payment for the attorney’s own services | $600 | Confused with legal fees, which go on the 1099-NEC; and it also pushes the recipient deadline back |
| 11 | Fish purchased for resale, if that is your trade or business | $600 | Skipped because the payment was under $2,000 — this box never moved either |
| 12 | Section 409A deferrals | Optional — the IRS does not require this box | Time spent completing a box nobody has to file |
| 13a | Cash tips — a dollar amount already included in Box 3 | — | Added to Box 3 rather than broken out of it, double-counting the payment |
| 13b | Treasury Tipped Occupation Code — a code, not an amount. Up to two | — | A dollar figure entered where a code belongs |
| 14 | Qualified overtime compensation — also already included in Box 3 | — | Same double-count as 13a |
| 15 | Nonqualified deferred compensation | — | Assumed to be new; it was already Box 15 on the April 2025 form |
| 16–18 | State tax withheld, state identification number, state income | — | State number omitted, which is what most state rejections are |
The three new boxes, and the mistake they invite
Boxes 13a, 13b and 14 arrived for tax year 2026 alongside the same boxes on the 1099-NEC and the W-2. The trap is the same on all three forms.
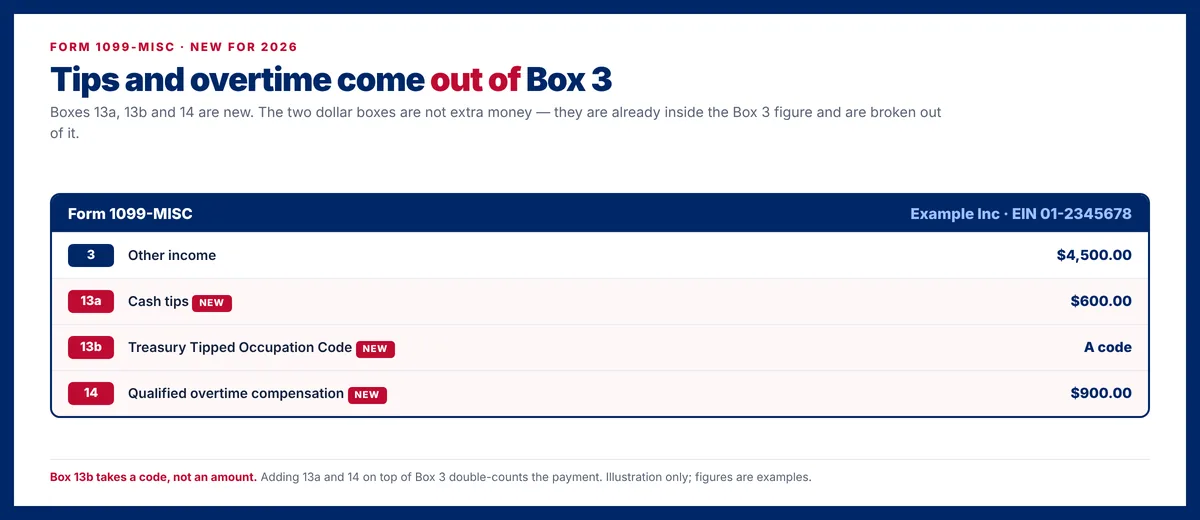
Boxes 13a and 14 are not extra money. If you paid someone $4,500 of other income and $600 of it was cash tips, Box 3 still reads $4,500 and Box 13a reads $600. Adding them together reports $5,100 to the IRS and to the recipient, and the recipient's return will not agree with yours.
Box 13b takes a code, not a dollar figure. The Treasury Tipped Occupation Code identifies the kind of work the tips were earned in. Up to two codes may be entered. A dollar amount in this box is a validation failure, not a rounding problem.
Which deadline applies to your form
Most 1099-MISC recipient copies are due 1 February 2027. Two boxes change that, and only when they are the only boxes in use.
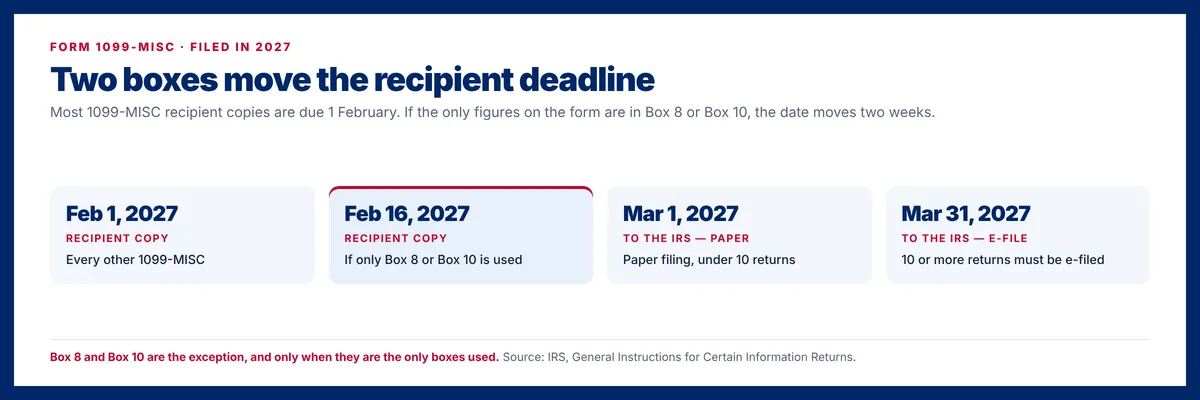
The IRS copy is due 1 March 2027 on paper and 31 March 2027 electronically. If you are filing ten or more information returns of any kind in the year — counting your W-2s, 1099-NECs and everything else together, not per form type — electronic filing is mandatory.
One more date worth knowing: the FIRE system closed on 19 November 2026. From 1 January 2027, IRIS is the only electronic channel the IRS operates for information returns.
1099-MISC or 1099-NEC?
The dividing line is services. If you are paying someone for work they did for your business, it is a 1099-NEC. If you are paying for something else — the use of property, a prize, a settlement passing through — it is usually a 1099-MISC.
| What you paid for | Form | Box |
|---|---|---|
| A contractor’s services | 1099-NEC | 1a |
| An attorney’s fees for their own services | 1099-NEC | 1a |
| Gross proceeds paid to an attorney in a settlement | 1099-MISC | 10 |
| Rent for office space or equipment | 1099-MISC | 1 |
| A prize or award not for services | 1099-MISC | 3 |
| Payments to a doctor, clinic or medical supplier | 1099-MISC | 6 |
| Royalties | 1099-MISC | 2 |
| Golden parachute payments | 1099-NEC | 3 (moved for 2026) |
| Anything paid by card or through a payment app | Neither — the processor files a 1099-K | — |
That last row is worth repeating: if you paid a contractor by credit card, PayPal or a similar network, you do not file a 1099 for it at all. Reporting it as well as the processor is how a recipient ends up with the same income on two forms.
Fill one in without signing up
The walkthrough below is the real filing screen with sample data in it. Nothing is submitted and nothing is filed — it is there so you can see where each of the boxes above actually lives before you commit to anything.
Which copy goes where
| Copy | Goes to |
|---|---|
| A | The IRS. If you e-file, this is produced for you — never print and post a downloaded Copy A. |
| 1 | The state tax department, where the state requires it. |
| B | The recipient, by 1 February 2027 (or 16 February for a Box 8 or Box 10 only form). |
| 2 | The recipient, to file with their state return. |
| C | You. Keep it for at least four years. |
Errors that get a return rejected or corrected
| What goes wrong | What happens |
|---|---|
| Name and TIN do not match IRS records | A CP2100 notice, and you may have to begin backup withholding |
| Box 13b holds an amount instead of a code | Schema validation failure — the transmission is rejected |
| Box 7 holds an amount instead of an X | Same — it is a checkbox |
| State income reported with no state identification number | State rejection, even where the federal return was accepted |
| Tips or overtime added to Box 3 rather than broken out of it | Accepted, then disputed by the recipient — the worst kind, because nothing tells you |
| A single-member LLC filed under the LLC name rather than the owner’s | TIN mismatch |
Correcting a 1099-MISC you have already filed
A wrong amount, a wrong code or a wrong checkbox is a one-step correction: file the same form again with the CORRECTED box ticked and the right figures in it. A wrong TIN or a wrong recipient name is a two-step correction — one form zeroing out the original, and a second carrying the correct details. The full procedure is in our guide to correcting a filed 1099.
Correct early. The penalty for a late or wrong information return rises with the delay, and the figures for returns filed in 2027 are published in Revenue Procedure 2025-32. We deliberately do not reprint them here, because they are indexed annually and a stale figure on a web page is worse than no figure — the IRS page linked in the sources below is always current.
Frequently asked questions
Is the 1099-MISC threshold now $2,000?
For rents, other income, medical and health care payments, and crop insurance proceeds, yes. Royalties and substitute payments are still $10. Gross proceeds to an attorney and fish purchased for resale are still $600. Direct sales is $5,000. Backup withholding and fishing boat proceeds are reportable at any amount.
Do I file a 1099-MISC for a corporation?
Usually not, but Box 6 is the exception that matters: medical and health care payments are reportable to corporations. Gross proceeds paid to an attorney in Box 10 are reportable to an incorporated law firm as well.
Do Boxes 13a and 14 get added to Box 3?
No. They are already included in Box 3 and are broken out of it. Adding them double-counts the payment.
What goes in Box 13b?
A Treasury Tipped Occupation Code — a code identifying the kind of work the tips were earned in, not a dollar amount. Up to two codes may be entered.
When is the recipient copy due?
1 February 2027, unless the only boxes used are Box 8 or Box 10, in which case it is 16 February 2027.
What is the difference between Box 10 and legal fees?
Box 10 is money passing through an attorney — a settlement paid to their trust account on behalf of a client. Payment for the attorney’s own services is nonemployee compensation and goes on the 1099-NEC.
I paid a contractor by credit card. Do I file?
No. The payment network reports it on a 1099-K. Filing a 1099-MISC as well reports the same income twice.
Can I download Copy A and post it?
No. The downloadable Copy A is for information only and the IRS will not accept a printed version. If you are filing ten or more information returns in total, you must e-file in any case.
Sources
- IRS, Instructions for Forms 1099-MISC and 1099-NEC (Rev. December 2026) — box definitions and every threshold quoted above
- IRS, General Instructions for Certain Information Returns — deadlines, the Box 8 and Box 10 extension, and the copy distribution
- IRS, About Form 1099-MISC
- IRS, Information return penalties — the current figures, rather than a copy of them
- IRS, E-file information returns — the ten-return electronic filing requirement and IRIS
- What changed for tax year 2026 — our summary of the OBBBA thresholds, the new boxes and the FIRE retirement
Disclaimer:
“This content is for informational purposes only and does not constitute legal, tax, or financial advice. For advice specific to your situation, consult a qualified US attorney or CPA.”

File Information Returns With Confidence
TaxFormHero supports 20+ IRS information returns, including 1099 and W-2 forms, with bulk Excel import, name/TIN matching and encrypted recipient delivery.
Explore TaxFormHero